Corporate Fixed Deposit Companies in India: Track Record, Safety and Trustworthiness
If you are considering recommending corporate fixed deposits to clients seeking regular monthly income, it is important to distinguish a well-known company from a financially safe deposit investment.
Corporate fixed deposits can offer attractive interest rates and monthly interest payouts. However, unlike eligible bank deposits, corporate FDs generally do not carry DICGC deposit insurance. Even a large, established company can face financial difficulties, so principal repayment is not guaranteed.
For investors seeking predictable income, I would evaluate corporate FDs based on three key factors:
-
Credit rating: Prefer the highest available long-term rating, typically AAA, while checking the rating agency’s latest outlook and rationale.
-
Financial strength and repayment history: Review audited financial statements, debt levels, liquidity and past repayment performance.
-
Regulatory compliance: Confirm that the company is legally permitted to accept the specific type of deposit and review the latest deposit terms.
Corporate FD companies to investigate
The following are established names whose deposit programmes are worth checking. This is a shortlist for due diligence, not a guarantee that every company’s current FD is available or carries an AAA rating.
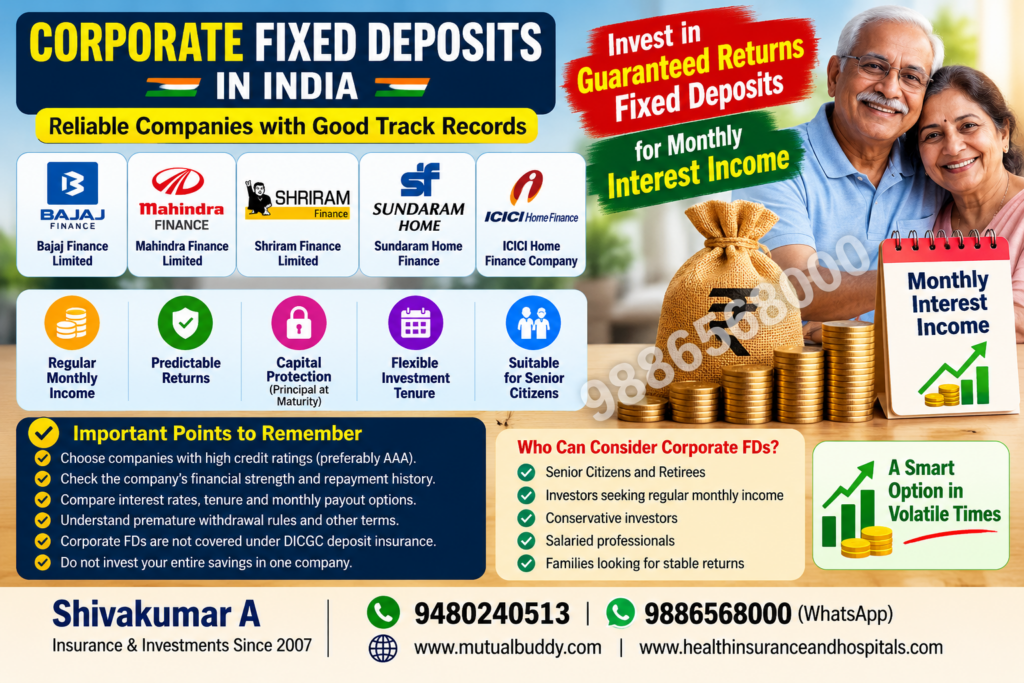
1. Bajaj Finance Limited
An established NBFC with a corporate fixed-deposit programme. Check the latest FD-specific rating, monthly payout rates and premature withdrawal terms.
A long-established financial services company with a deposit programme. Its FD rating has been reported as AAA by multiple agencies in published product listings; verify the latest rating directly.
3. Shriram Finance Limited
A major retail and commercial vehicle financier that offers company deposits. ICRA’s published rating information includes an AAA (Stable) rating for its long-term fixed-deposit programme. Confirm the current FD-specific rating and terms before investing.
4. Sundaram Home Finance
A housing finance company worth investigating for its deposit terms and rating history. Published rating summaries have reported an AAA rating; confirm whether a current public deposit scheme is available.
5. ICICI Home Finance Company
Another established housing finance company to investigate. A published rating summary has reported an AAA rating, but you should check the current deposit programme, eligibility and rating before placing funds.
How to verify the safety of a corporate FD
Use these checks before recommending any deposit to a client.
| Check | What to look for |
|---|---|
| Credit rating | Current AAA rating specifically for the fixed-deposit programme, not just the company’s bonds |
| Rating outlook | Stable outlook and no recent downgrade or negative watch |
| Repayment history | Public disclosures about delayed payments, defaults and complaints |
| Financial position | Audited accounts, liquidity and debt-servicing capacity |
| Deposit terms | Monthly interest option, tenure, premature withdrawal and renewal rules |
| Insurance | Understand that NBFC deposits are not covered by DICGC insurance |
DICGC confirms that deposits raised by NBFCs are excluded from its deposit insurance protection. Eligible bank deposits are insured up to ₹5 lakh per depositor per bank, including principal and interest, subject to the applicable rules.
You can verify credit ratings through CRISIL Ratings and ICRA.
My practical recommendation
For clients who depend on their savings for monthly household expenses, compare high-quality corporate FDs with insured bank FDs before deciding. Avoid concentrating a client’s entire retirement corpus in one company merely to earn a higher interest rate.
One important question: Are you looking for corporate FDs to recommend to your clients, or for your own investment?
That distinction matters because I can prepare a more useful shortlist with current monthly payout rates, available tenures, senior-citizen rates and FD-specific credit ratings.
